
How to Manage Money Like the 1% is less about looking wealthy and more about creating a system that gives every part of your income a clear purpose. Instead of allowing your entire salary to disappear into bills, lifestyle expenses and impulse purchases, you can divide your money between building wealth, protecting yourself, covering essential expenses and enjoying life.
A popular framework discussed in the source material is the 25-15-50-10 rule. It divides income into four broad purposes: 25% for growth, 15% for financial stability, 50% for essential expenses and 10% for enjoyment. It is best viewed as a budgeting framework rather than a universal formula that every wealthy person follows.
Table of Contents
What Does “Managing Money Like the 1%” Actually Mean?
The phrase “manage money like the 1%” can sound as though wealthy people follow one secret investment strategy. In reality, there is no single money-management formula followed by every high-net-worth individual.
The useful idea behind the phrase is ownership and financial structure.
The supplied source highlights entrepreneurs, investors, people with inherited wealth, and individuals with valuable specialized skills as different groups that can build or possess assets. The broader lesson is to gradually move beyond depending entirely on active income and to build financial assets, skills or other sources of value.
That does not mean everyone needs to start a business or make risky investments. It means giving part of your income a long-term purpose instead of spending everything immediately.
The 25-15-50-10 Money Management Framework
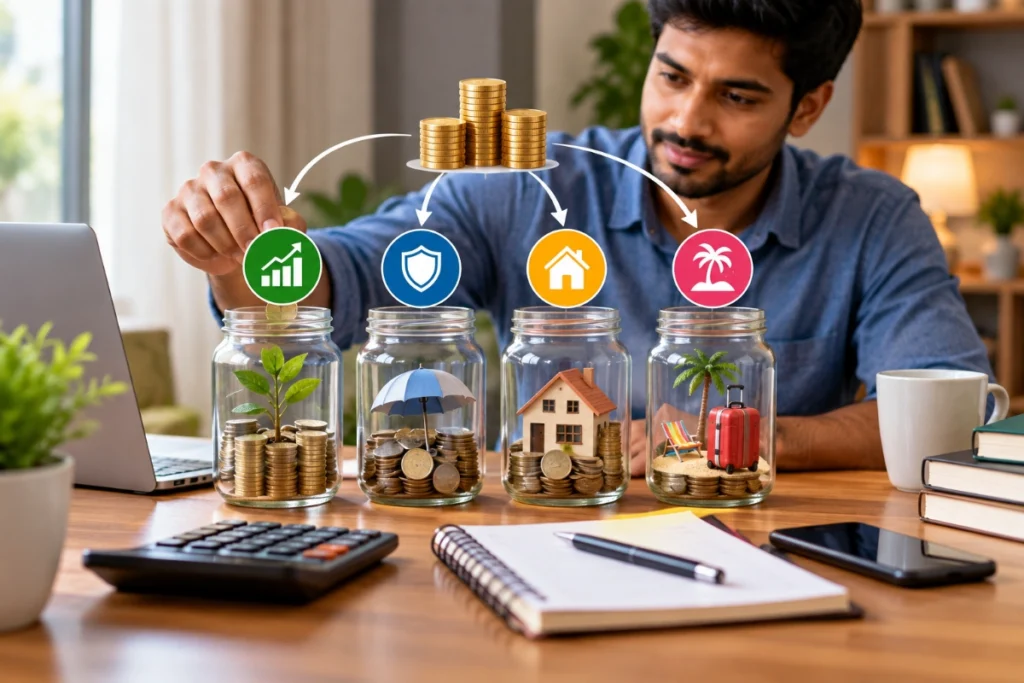
The framework can be understood as four financial buckets:
| Income Allocation | Purpose | Main Goal |
|---|---|---|
| 25% | Growth | Build long-term wealth |
| 15% | Stability | Create an emergency fund |
| 50% | Essentials | Cover necessary expenses |
| 10% | Enjoyment | Spend on things that improve your life |
The percentages are not a mandatory financial rule. Your actual allocation may need to change depending on income, debt, family responsibilities, location, financial goals and risk tolerance.
The important principle is to assign your money a purpose before you spend it.
1. Put 25% Toward Growth
The first major principle is to direct part of your income toward long-term growth.
The source recommends allocating 25% toward assets or opportunities that can potentially grow in value or generate income. Examples mentioned include mutual funds, shares, real estate and investing in skills.
The right choice depends on your financial situation and knowledge. Investments can lose value, and past performance does not guarantee future returns.
For someone considering mutual funds, it is important to understand what the particular fund invests in, its costs, risks, investment horizon and suitability for the individual’s goals.
Why Starting Early Matters
Time can be an important part of long-term investing.
Consider two hypothetical investors:
- Ravi starts investing ₹2,000 per month at age 20.
- Kiran starts at age 30 and invests ₹3,000 per month.
- Both continue until age 60.
The source uses a hypothetical 12% annual return to demonstrate the effect of starting earlier. Under that assumption, Ravi’s investment could grow to roughly ₹2.35 crore, while Kiran’s could reach roughly ₹1 crore.
However, 12% should not be treated as a guaranteed return. Actual investment returns vary, and the result of a hypothetical calculation depends heavily on the assumed rate, investment period and consistency of contributions.
The more reliable lesson is simply that starting earlier can give investments more time to compound.
Investing in Yourself Also Counts
Growth does not always mean buying financial assets.
Learning a valuable skill can potentially increase your future earning capacity. For example, improving technical, communication, business or professional skills may help you qualify for better opportunities.
The important question is:
Can this use of money increase my future financial capacity?
2. Keep 15% for Financial Stability
Building wealth is difficult if one unexpected expense forces you to sell investments or borrow at expensive interest rates.
That is why the second bucket is financial stability.
The source recommends using 15% of income toward an emergency or stability fund until an appropriate safety cushion has been created.
An emergency fund is meant for unexpected needs such as medical expenses, urgent repairs or temporary loss of income. It should not be treated like an investment portfolio whose main purpose is to maximize returns.
How Much Should an Emergency Fund Hold?
There is no single amount that works for everyone.
Start by calculating your essential monthly expenses.
For example, suppose your necessary expenses are:
- Rent or housing costs: ₹15,000
- Food and groceries: ₹5,000
- Utilities and internet: ₹3,000
- Transportation: ₹2,000
That gives you ₹25,000 of essential expenses per month.
A five-month emergency reserve would therefore be:
₹25,000 × 5 = ₹1,25,000
Some people may prefer a larger reserve depending on job stability, dependants, health considerations and other circumstances.
The source emphasizes that emergency money should remain accessible and should not be exposed to unnecessary market volatility.
Automate Your Emergency Savings
One practical approach is to set up an automatic transfer immediately after receiving your income.
For example:
Salary received → 15% automatically transferred → emergency savings
Automation reduces the need to make the same saving decision every month.
If you withdraw money from the emergency fund, another useful rule is to replenish the amount later.
For example, if you use ₹5,000 for an emergency, make rebuilding that ₹5,000 part of your subsequent savings plan.
3. Keep Essential Expenses Within 50%
The third part of the framework is controlling essential expenses.
The source suggests keeping around 50% of income for necessities such as housing, food, utilities, transportation and necessary insurance.
This does not mean every person must spend exactly 50%.
Someone living in an expensive city may have unavoidable housing costs above that level. Another person living with family may have substantially lower expenses.
The useful principle is to distinguish needs from lifestyle upgrades.
What Counts as an Essential Expense?
Typical essentials can include:
- Basic housing
- Groceries and necessary food
- Electricity and other utilities
- Internet or communication services needed for work or daily life
- Public transportation or necessary vehicle costs
- Essential insurance
- Required debt payments
Some expenses can fall into a grey area depending on your circumstances.
For example, a car may be essential for one person’s job but unnecessary for another person who has reliable public transportation.
Avoid Lifestyle Inflation
One common problem is increasing expenses whenever income increases.
Suppose someone receives a significant salary increase and immediately upgrades:
- Their phone
- Their car
- Their apartment
- Their subscriptions
- Their dining habits
Their income has increased, but their ability to build wealth may not improve much.
A better approach is to allow some lifestyle improvement while directing part of the additional income toward savings, investments or other financial goals.
This is often called avoiding lifestyle inflation.
Be Careful With Expensive Vehicles
Vehicles can become a major financial burden because the purchase price is only one part of ownership.
A vehicle can also involve:
- Loan payments
- Fuel
- Insurance
- Maintenance
- Repairs
- Parking
- Depreciation
If a vehicle is necessary, compare the total cost with your income and financial goals rather than choosing one primarily for status.
A used vehicle may sometimes reduce the initial purchase cost, but its condition, maintenance history and ownership costs should still be evaluated carefully.
4. Use 10% for Enjoyment
A financial plan should not mean eliminating every enjoyable expense.
The fourth bucket in the framework assigns 10% toward enjoyment and personal rewards.
This could include:
- A family outing
- Travel
- Hobbies
- Dinner with friends
- Gifts
- Entertainment
- Personal interests
The purpose is to create room for enjoyment without allowing lifestyle spending to consume money intended for essential expenses, emergencies or long-term goals.
One practical method is to keep this money in a separate account.
When the allocated amount is used, you wait until the next planned allocation rather than taking money from your emergency fund.
Use a 7-Day Rule for Impulse Purchases
One of the practical spending ideas in the source is the seven-day rule.
If you see something you want but do not immediately need, wait seven days before buying it.
After seven days, ask yourself:
- Do I still need it?
- Will I actually use it?
- Does it solve a real problem?
- Is the quality worth the price?
- Could the money be used for something more important?
The waiting period can help separate a temporary impulse from a genuine need.
For smaller purchases, you can adapt the waiting period to your situation. The goal is not the number seven itself; the goal is to create a pause between wanting something and paying for it.
Focus on Value, Not Just Brand Names
A higher price does not automatically mean better value.
Imagine buying a ₹1,000 pair of shoes and wearing them 100 times. The purchase cost works out to ₹10 per use.
If another pair costs ₹10,000 but is used only twice, its cost per use is ₹5,000.
This is a simplified example, but it demonstrates an important spending question:
How much value will I actually get from this purchase?
Price, durability, frequency of use and quality all matter.
Automate Your Money System
One of the simplest ways to make a financial plan easier to follow is automation.
Instead of waiting until the end of the month to see what remains, assign money to different purposes when income arrives.
A simplified system could look like this:
Income arrives
↓
25% → Growth
15% → Emergency/Stability
50% → Essentials
10% → Enjoyment
The exact percentages can be adjusted to fit your circumstances.
Automation can be particularly useful because it reduces the number of financial decisions you need to make repeatedly.
What If You Cannot Follow 25-15-50-10?
Do not treat the framework as a pass-or-fail test.
If your current income does not allow you to invest 25%, start with an amount that is realistic.
If essential expenses already consume more than 50%, focus first on understanding where the money is going and whether any costs can reasonably be reduced.
If you have high-interest debt, your priorities may also be different.
Personal finance is personal. A budgeting framework should help you organize your money, not make you feel financially successful or unsuccessful based on whether you hit an arbitrary percentage.
A Simple Monthly Money Routine
You can turn the framework into a monthly routine:
Step 1: Know Your Take-Home Income
Use the amount that actually reaches your bank account after applicable deductions.
Step 2: List Essential Expenses
Write down housing, food, utilities, transportation, insurance and other genuine necessities.
Step 3: Set Your Emergency Fund Target
Calculate your essential monthly expenses and decide how much emergency savings is appropriate for your circumstances.
Step 4: Automate Savings and Investments
Schedule transfers around your income date so that saving does not depend entirely on willpower.
Step 5: Control Lifestyle Spending
Review subscriptions, unnecessary purchases and large recurring expenses.
Step 6: Keep Some Money for Enjoyment
Give yourself a defined amount that can be spent without guilt, provided essential obligations and financial priorities are being handled.
Step 7: Review Every Month
At the end of each month, check:
- How much did I earn?
- How much did I spend?
- How much did I save?
- How much did I invest?
- Did my emergency fund grow?
- Which expenses can be improved next month?
Also Read:How to Manage Money Like the Top 1%
Frequently Asked Questions
Is the 25-15-50-10 rule an official rule used by the 1%?
No. It should not be presented as an official financial rule used by every wealthy person. It is a budgeting framework described in the supplied source and can be used as a way to organize income.
What is the main idea behind How to Manage Money Like the 1%?
The main idea is to give your income different jobs instead of spending everything that comes into your account. The framework emphasizes wealth building, financial protection, essential expenses and controlled enjoyment.
Should I invest 25% of my income?
Not necessarily. The 25% allocation is a framework, not a universal requirement. Your appropriate amount depends on your income, expenses, debt, emergency savings, goals and risk tolerance.
How much emergency savings should I have?
There is no single amount that applies to everyone. A useful starting point is to calculate your essential monthly expenses and build an emergency reserve based on your employment stability, dependants and other personal circumstances.
Should emergency money be invested in stocks?
Emergency money generally needs accessibility and stability rather than maximum growth. Investments exposed to significant market fluctuations may not be appropriate for money you may need immediately. Consider the purpose and liquidity of the account before choosing where to keep emergency savings.
What should I do if I cannot save 25%?
Start with an amount you can realistically maintain. Review your essential expenses, unnecessary recurring costs and debt obligations. Increasing your savings rate gradually can be more practical than setting an unrealistic target and abandoning the plan.
Does earning more automatically make someone wealthy?
No. A higher income can provide greater financial capacity, but spending patterns, savings, debt, investing, asset ownership and long-term financial decisions also affect financial outcomes.
Is investing in mutual funds risk-free?
No. Mutual funds involve investment risk, and the level of risk depends on the type of fund and its underlying investments. Investors should understand the scheme and its risks before investing.
How can I stop impulse spending?
Create a delay between wanting something and purchasing it. A seven-day waiting rule for non-essential purchases can be one practical approach. You can also remove unnecessary shopping notifications and avoid storing payment details for impulse purchases.
Should I stop spending money on entertainment?
No. A sustainable financial plan should leave room for reasonable enjoyment. The key is to decide how much you can spend without compromising essential expenses, emergency savings and long-term financial goals.
Conclusion
Managing money like the 1% does not require pretending to be rich or copying the lifestyle of wealthy people.
The more useful lesson is to build a financial system in which your money has a purpose.
The 25-15-50-10 framework provides one possible structure:
- 25% for growth
- 15% for stability
- 50% for essential expenses
- 10% for enjoyment
You do not have to follow those percentages perfectly. Start with your actual income and expenses, build financial stability, avoid unnecessary lifestyle inflation and gradually increase the amount directed toward long-term goals.
The goal is not to look wealthy today. It is to build a financial position that gives you more choices in the future.
Also Read:New EPFO Rule 2026 Explained

